Before You Buy Down Your Mortgage Rate, Ask These 5 Questions
A lower rate isn’t free. Here are the five questions to ask before you pay points or spend a seller credit, including the 30-second break-even math.
Before You Buy Down Your Mortgage Rate, Ask These 5 Questions
By Frank Burks II, Certified Mortgage Advisor | The Burks Lending Group empowered by NEXA Lending
That lower mortgage rate looks good. But what did it cost you?
Before you spend a few thousand dollars chasing a smaller payment, ask whether the savings will catch up before you sell or refinance. And if a seller or builder is covering the cost, ask what else that money could do for you.
A lower rate can be a smart move. The number alone doesn’t tell you whether it’s your best move.
Across Smyrna, Murfreesboro, Nashville and the rest of Middle Tennessee, buyers face this decision: bring more money to closing for a lower payment, or keep more cash available and accept a higher payment.
Neither choice wins automatically.
After 25 years in mortgage lending, here’s what I want buyers to understand: getting to closing matters, but so does having a mortgage and a savings cushion you can live with afterward.
Before you buy down your rate, ask these five questions.
1. What am I paying to get that lower rate?
When you pay discount points, you pay an upfront charge in exchange for a lower interest rate.
One point equals 1% of your loan amount. On a $300,000 mortgage, that’s $3,000.
But one point does not equal a fixed reduction in your rate. The reduction depends on the lender, loan program and market pricing.
That’s why comparing two advertised rates can leave you with half the story.
One offer might include thousands of dollars in points. Another might have no discount points. A third might include a lender credit tied to a higher rate to help offset eligible closing costs.
Ask for written options using the same loan amount, loan type, term, down payment and lock period. Request pricing from the same day when possible.
Then compare:
The interest rate and APR.
Discount points and other lender charges.
Any lender credits.
Monthly principal and interest.
The estimated total payment, including applicable taxes, insurance and mortgage insurance.
The estimated cash needed at closing.
For a standard Loan Estimate, discount points appear on page 2, Section A. That gives you a specific place to look instead of hunting through the fine print.
A zero-point loan still has closing costs. It simply means you aren’t paying discount points for that rate.
Now you’re comparing the financing behind the headline.
2. How long will it take the savings to repay the cost?
Start with this calculation:
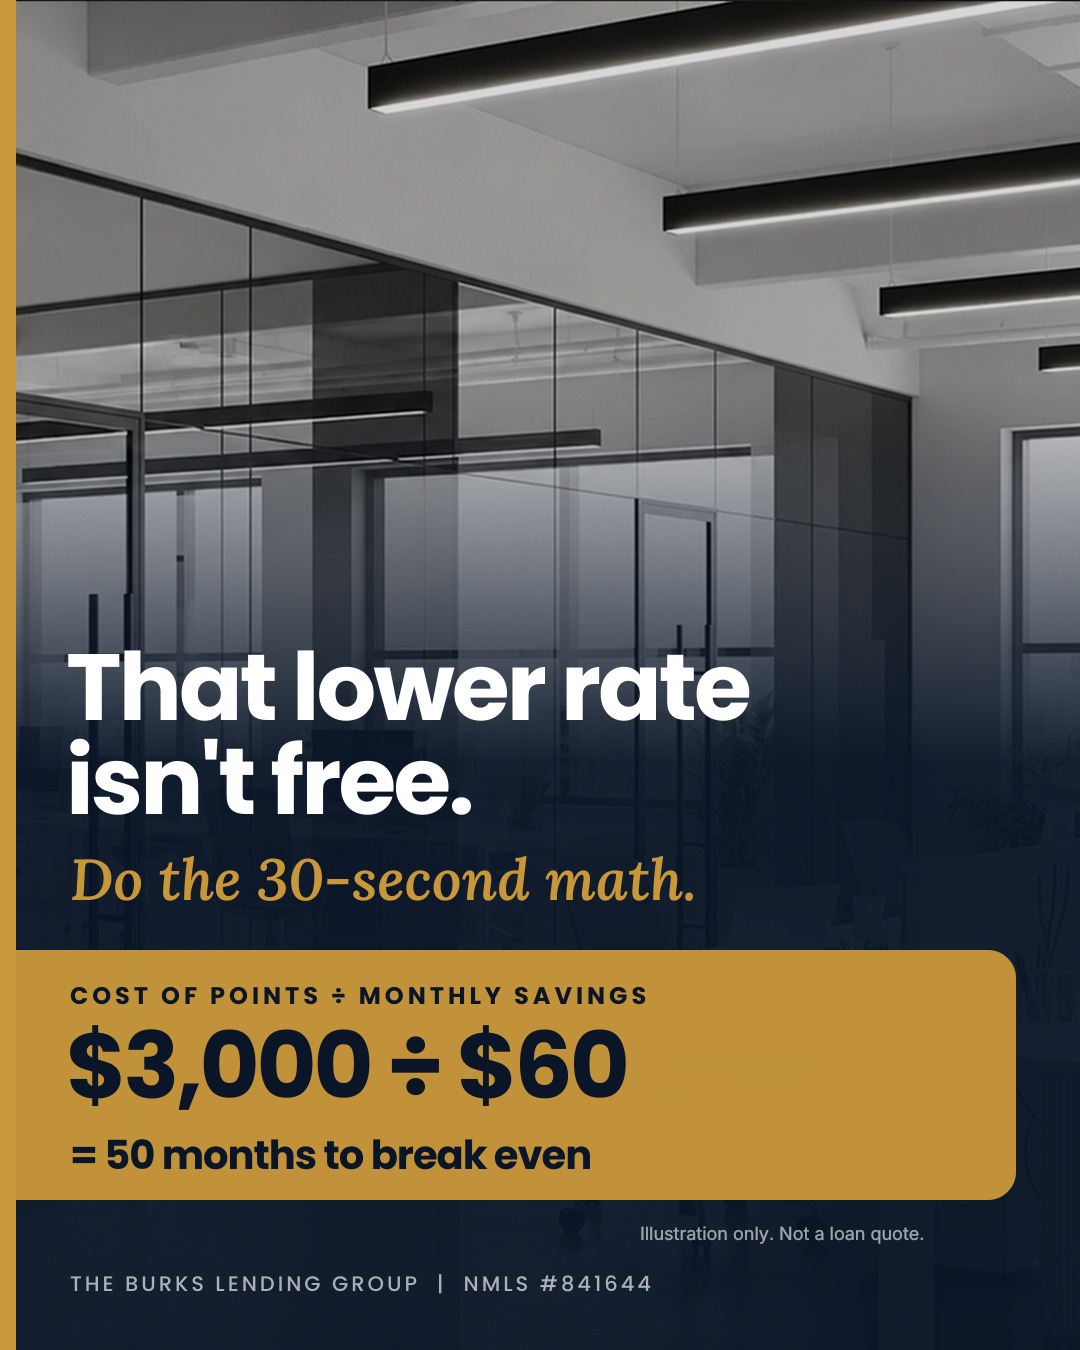
Additional upfront cost ÷ monthly payment savings = simple break-even period
Suppose two otherwise comparable options differ by $3,000 in upfront cost, and the lower-rate option saves $60 a month in principal and interest.
$3,000 ÷ $60 = 50 months
That’s four years and two months before the payment savings recover the additional cost.
Here’s how that illustration looks over time:
| How long you keep the loan | Cumulative payment savings | Savings minus the $3,000 upfront cost |
|---|---|---|
| 2 years | $1,440 | −$1,560 |
| 4 years | $2,880 | −$120 |
| 5 years | $3,600 | +$600 |
| 7 years | $5,040 | +$2,040 |
This is a hypothetical example, not a rate quote. It assumes a constant $60 monthly savings and excludes differences in remaining loan balances, investment returns on retained cash and tax effects.
The important question is:
How long do I expect to keep this mortgage?
You could live in the house for ten years and refinance the loan after two. In this illustration, you would replace the mortgage before recovering the extra upfront cost through payment savings.
That doesn’t mean paying points is always wrong. It means your expected loan timeline belongs in the decision.
I like comparing a shorter timeframe, a longer timeframe and the timeframe you consider most likely. Life doesn’t always follow the spreadsheet, so let’s see how the choice holds up under more than one possibility.
3. Could my seller credit do more for me somewhere else?
A seller credit can help with eligible closing costs, prepaid expenses or discount points, subject to your loan program’s rules and contribution limits. It generally cannot cover your required down payment.
But every dollar has a job. If you use it for points, that same dollar isn’t also covering your title charges or other eligible expenses.
Picture a buyer with a $9,000 seller credit and two possible financing structures.
Option A: Apply more of the credit toward eligible closing expenses. The buyer brings less of their own money to closing and keeps more savings available.
Option B: Apply some of the credit toward discount points. The buyer receives a lower rate but may need more personal funds for the remaining closing expenses.
Which one is better?
We need the numbers before we answer.
A buyer with limited savings may place more value on keeping cash for moving expenses, repairs and an emergency fund. The mortgage payment won’t be the only bill arriving at the new address.
A buyer with comfortable reserves and a longer expected loan timeline may place more value on reducing the monthly payment.
And sometimes the credit can cover eligible closing expenses and help pay for points. We should review that possibility too.
Here’s the question I want you asking:
“If I use this credit to lower my rate, how does that change the money I bring to closing and the savings I have afterward?”
Seller-funded points aren’t the same as writing a separate check for points out of your own pocket. Still, compare what you gain with what you give up by using the credit that way.
Ideally, have this conversation before finalizing your offer.
4. Is this a permanent rate reduction or a temporary payment subsidy?
Builder incentives deserve a close look because two offers can sound similar and work very differently.
A permanent buydown uses discount points to lower the mortgage’s actual interest rate. On a fixed-rate loan, that reduced rate remains in place for the life of that loan.
A temporary buydown helps fund part of your payment for a limited period. It does not change the interest rate written in your mortgage note.
With a standard fixed-rate 2-1 buydown:
During year one, your principal-and-interest contribution is calculated using a rate two percentage points below the note rate.
During year two, it is calculated using a rate one percentage point below the note rate.
Beginning in year three, you make the full principal-and-interest payment at the note rate.
Funds deposited upfront cover the scheduled difference during the buydown period.
These descriptions address principal and interest. Taxes, homeowners insurance, mortgage insurance and HOA dues also affect your housing budget. A temporary buydown does not freeze those expenses.
Ask for a written breakdown of your estimated total housing payment in years one, two and three.
Then ask:
Is the incentive a temporary buydown, permanent discount points, closing-cost assistance or a combination?
Must I use a particular lender to receive it?
How do the full costs compare with another financing option?
Which payment does the lender use to qualify me?
What does the buydown agreement say happens to unused funds if the loan is paid off early?
For Fannie Mae loans with a temporary buydown, qualification is based on the note rate. Other programs have their own requirements.
The builder’s preferred financing package may be competitive. Give it a fair comparison that includes the incentive, lender charges, cash needed and ongoing payment.
And please don’t build your budget around this sentence:
“I’ll just refinance before year three.”
A future refinance depends on available rates, your qualifications, the property’s value and the cost of the new loan. None of those is guaranteed today.
Buy with a payment you can manage if the current mortgage stays in place. If refinancing later makes financial sense, we can evaluate it then.
5. Does my rate lock cover my actual closing timeline?
Your rate lock and your contract closing date need to work together.
A lock protects specified pricing for a set period, subject to its terms and changes to your application. It does not automatically extend because your closing gets delayed.
Before locking, ask:
When does the lock expire?
Does that leave enough time for the expected closing?
What happens if we need an extension?
What fees or pricing changes could apply?
Is a float-down option available, and what are its conditions?
Which changes to my loan or application could affect the locked pricing?
On new construction, discuss the expected completion date and any remaining steps required before closing.
On a resale purchase, account for underwriting, appraisal, title work and other outstanding conditions.
A rate is only useful if we understand what it takes to get that pricing to the closing table.
Frequently Asked Questions
Is paying mortgage points worth it?
It can be, depending on the additional cost, payment savings, how long you keep the loan and how much cash you need available. Compare options over several possible loan timelines before deciding.
How do I calculate the break-even period?
Divide the additional upfront cost by the monthly payment savings. For example, $3,000 divided by $60 equals 50 months. This simple calculation measures payment savings and leaves out other financial effects.
Can a seller credit pay for discount points?
Generally, yes, subject to the loan program’s rules, contribution limits and eligible costs. Compare using the credit for points with using it for other eligible closing expenses.
Does a 2-1 buydown change my mortgage’s actual rate?
A standard temporary 2-1 buydown does not change the note rate. Upfront funds supplement your payments during the first two years. Beginning in year three, you make the full principal-and-interest payment.
Will my total payment stay the same after a permanent buydown?
On a fixed-rate loan, the principal-and-interest payment generally remains the same. Taxes, insurance and other applicable housing expenses can change.
What happens if my rate lock expires before closing?
Depending on the lender and lock agreement, you may need an extension or different pricing. Ask about the terms and potential costs before locking.
Bring Me the Numbers. Let’s Compare the Options.
Have a Loan Estimate, builder incentive sheet or quote you’re trying to make sense of?
Bring it with you.
We’ll compare the upfront cost, monthly payment, expected loan timeline and money you’ll have available after closing.
If you’re buying in Smyrna, Murfreesboro, Nashville or elsewhere in Middle Tennessee, book a conversation with me. We’ll talk through what you’re trying to accomplish and the financing choices in front of you.
A lower rate is a tool, not a trophy. Let’s make sure it does the job you need.
Everybody Deserves a Key. Clear to Close Starts Here.
Frank Burks II, Certified Mortgage Advisor | NMLS #841644
The Burks Lending Group empowered by NEXA Lending | NMLS #1660690
Equal Housing Opportunity.
Examples are hypothetical illustrations, not loan offers or commitments to lend. Rates, fees, terms, eligibility and program availability vary. All loans are subject to applicable underwriting and approval requirements.